 Facebook
 X
 Pinterest
 Copy Link
The Fed Raised Rates—Should North Jersey Homebuyers Wait?
The Federal Reserve raised its benchmark interest rate by 0.25 percentage points on September 16—the first increase since 2023. That announcement immediately raised an important question for North Jersey homebuyers:
Should I buy now, or wait for mortgage rates to come down?
The honest answer is that waiting does not always produce the result buyers expect.
The Fed Does Not Directly Set Mortgage Rates
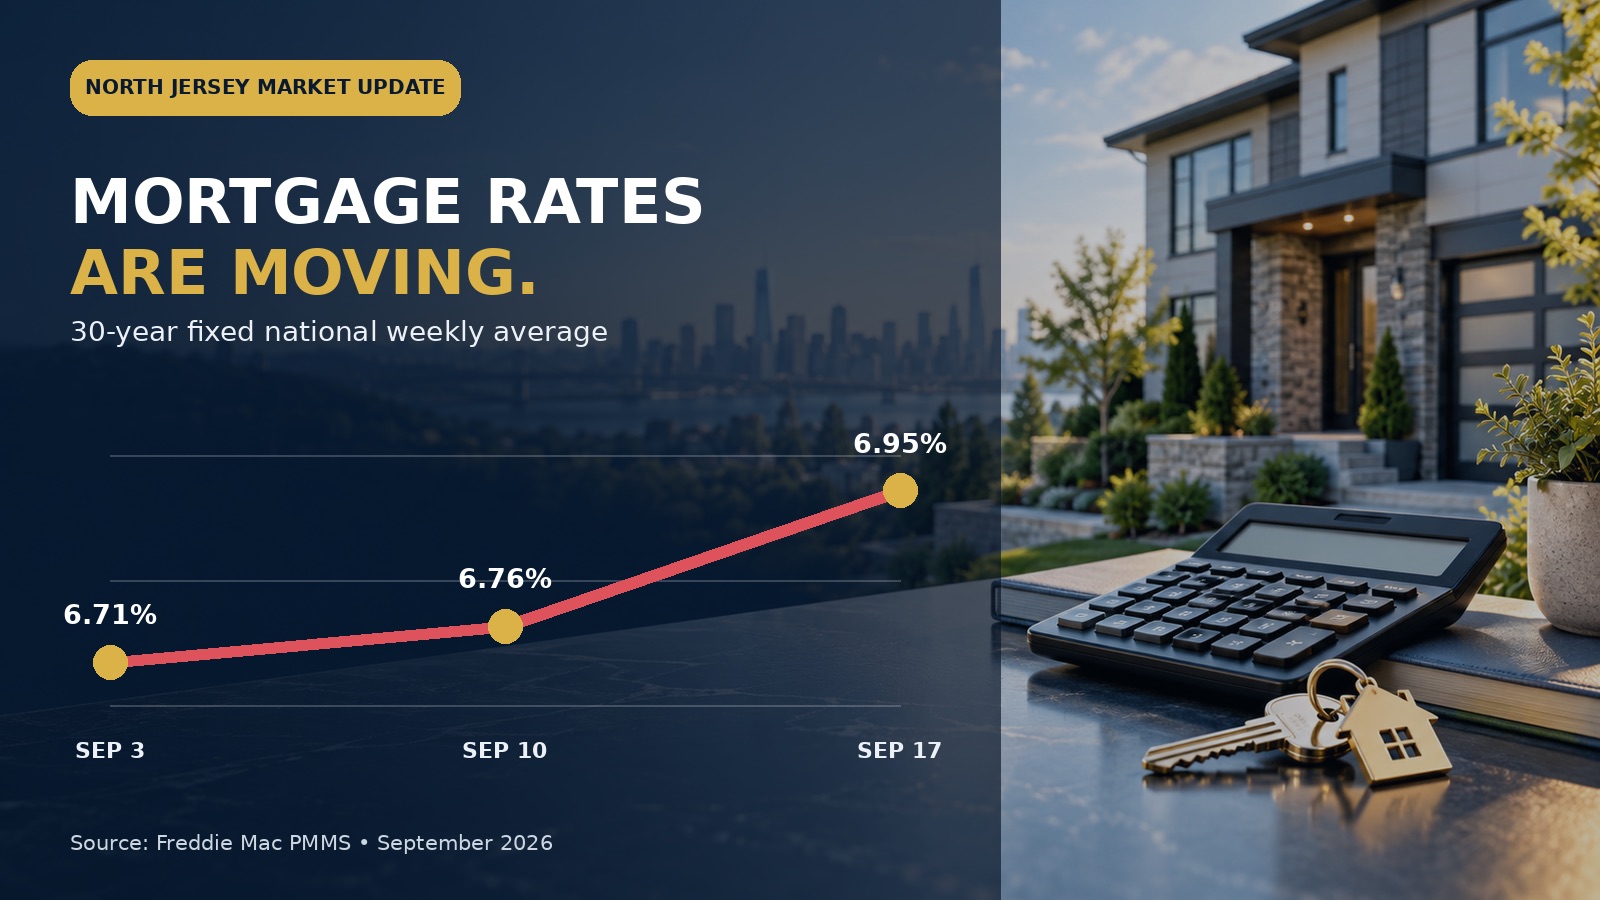
One of the most common misconceptions is that mortgage rates automatically move in the same direction, and by the same amount, as the Federal Reserve’s benchmark rate.
They don’t.
Mortgage rates are influenced by several factors, including inflation expectations, the bond market, economic growth and investor demand. In fact, the mortgage market frequently begins reacting before the Federal Reserve makes its official announcement.
According to Freddie Mac, the average 30-year fixed mortgage rate was 6.95% as of September 17, 2026. Individual rates will vary depending on a borrower’s credit, down payment, loan program, property and other financial factors.
What This Means for North Jersey Buyers
Higher borrowing costs affect affordability, but they don’t necessarily mean buyers should put their plans on hold.
A more productive approach is to determine:
- What monthly payment fits comfortably within your budget
- Which loan programs may be available to you
- Whether down-payment assistance could help
- How much negotiating leverage exists in your target market
- Whether a seller-paid rate buydown or closing-cost credit may be possible
Getting pre-approved does not obligate you to purchase a home. It gives you a clearer understanding of your options and allows you to act quickly if the right property becomes available.
That preparation can be particularly important in Northern New Jersey, where properly priced homes in desirable areas can still attract strong interest.
Should You Wait for Rates to Fall?
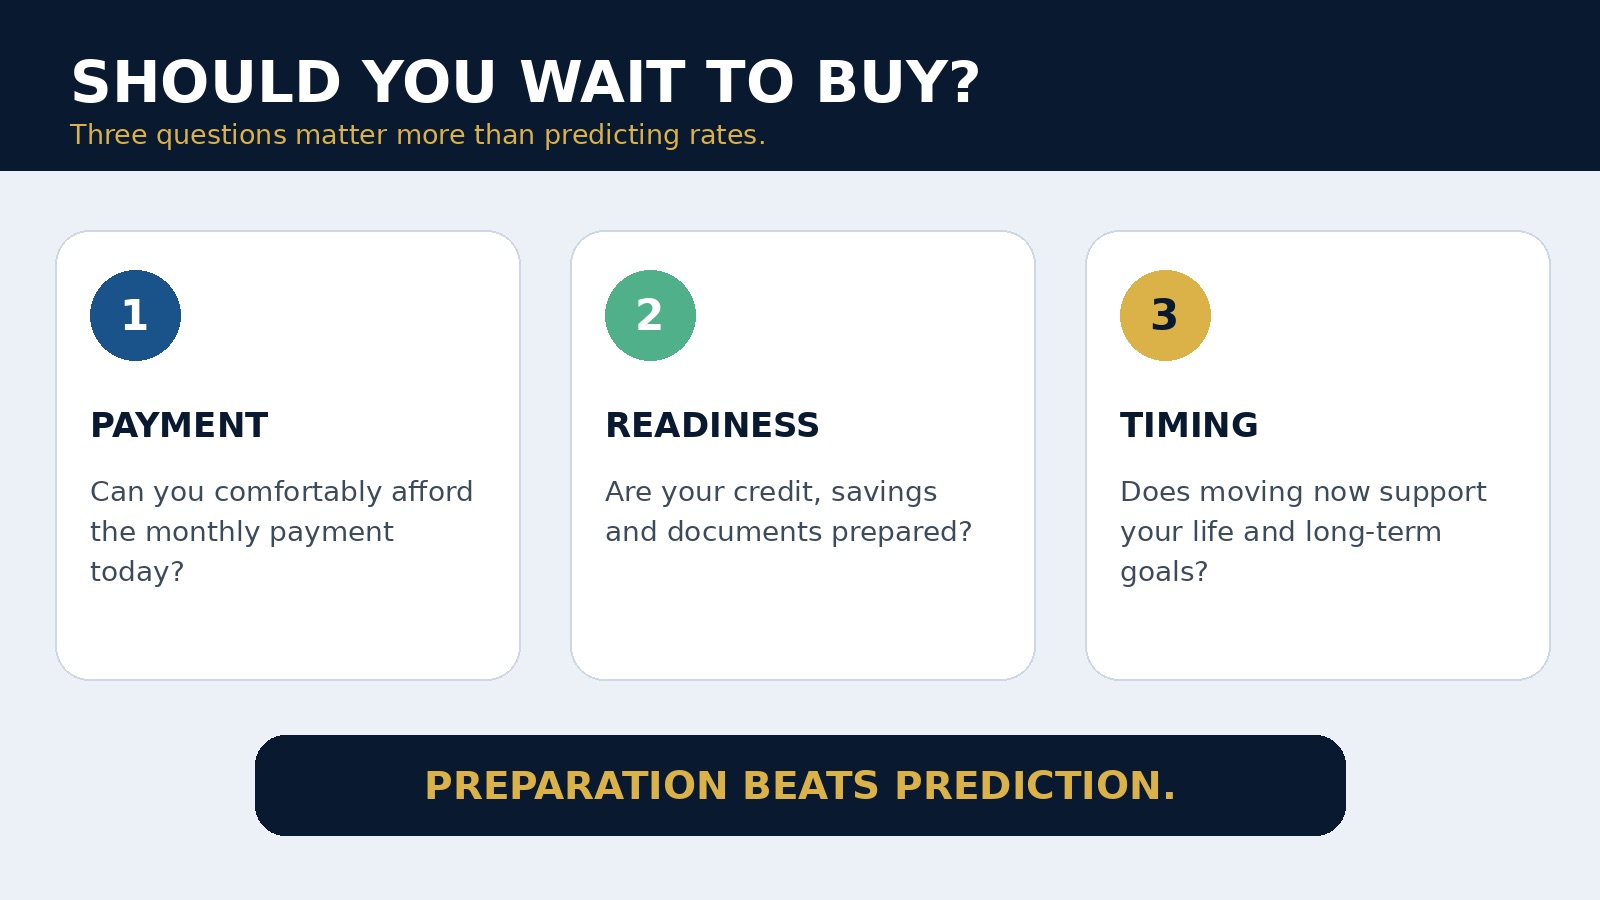
Waiting can make sense when you need time to improve your credit, increase your savings or strengthen your overall financial position.
Waiting solely because you expect mortgage rates to drop, however, carries risk. Rates could remain elevated or move higher. If rates eventually fall, increased buyer demand could also create more competition and place upward pressure on home prices.
Instead of trying to predict the perfect week to buy, consider building a plan around your finances, needs and long-term goals.
What Sellers Should Know
Mortgage-rate changes matter to sellers, too.
Today’s buyers are highly payment-conscious. Proper pricing, strong presentation and a thoughtful negotiation strategy are especially important. Depending on the property and offer, a seller concession that helps reduce a buyer’s closing costs or interest rate may sometimes be more valuable than a comparable price reduction.
Every transaction is different, so these options should be evaluated with qualified real estate, lending and legal professionals.
The Bottom Line
A changing mortgage market does not mean you should panic—and it does not automatically mean you should stop looking.
It means you need accurate information, a realistic budget and a coordinated real estate and financing strategy.
If you are considering buying or selling in Passaic, Bergen, Hudson or the surrounding North Jersey markets, I would be happy to help you evaluate your options. For personalized financing information, I can also connect you with my trusted mortgage partner, Eric Estevez of CMG Home Loans.
Luis “Dennis” Davila
Broker-Salesperson, REALTOR®
Coldwell Banker Realty
📱 201-780-0498
🌐 www.dennis-davila.com
Mortgage rates and loan terms are subject to change and depend on individual borrower qualifications. This article is for general informational purposes and is not financial, tax or legal advice.